Buying a car is already a major expense, but the spending does not always stop when you drive away from the dealership. Repairs can appear years later, especially after the original factory warranty expires. This is why many dealers and warranty companies offer an extended car warranty. The idea sounds simple. You pay for extra protection now, and the warranty helps pay for certain repairs later. For drivers who worry about a sudden engine, transmission, or electrical problem, that promise can sound very attractive.
The problem is that extended warranties are not all the same. Some plans provide useful protection against expensive repairs, while others have so many limits that the owner receives little value. A cheap plan may cover only a few major parts. An expensive plan may offer wider protection but still exclude common maintenance and wear items. Before paying for extra coverage, you need to understand exactly what you are buying. Knowing what is covered, what is excluded, and what can become a waste of money can help you make a smarter decision.
What Is an Extended Car Warranty?
An extended car warranty is additional protection that may help pay for certain vehicle repairs after the original manufacturer warranty ends. Depending on the plan, coverage may focus only on major parts such as the engine and transmission, or it may include many electrical, mechanical, steering, suspension, and comfort systems. Coverage normally lasts for a specific number of years or until the vehicle reaches a certain mileage. Once either limit is reached, the protection usually ends.
The word warranty can sometimes make the product sound more complete than it really is. In practice, the exact protection depends on the written contract. Two plans with similar names can cover very different repairs. One may pay for an air conditioning compressor while another may exclude it. One may let you visit many repair shops while another may require an approved location. This is why drivers should never judge an extended warranty only by its name, advertising, or monthly price. The actual contract is what decides whether a repair will be covered.
Manufacturer Plans and Vehicle Service Contracts
Extra protection can come from the vehicle manufacturer, a dealership, or an independent company. Manufacturer plans are connected to the automaker and may allow repairs through authorized dealerships. Independent plans are often called vehicle service contracts. These contracts can also provide useful protection, but their rules, repair networks, payment methods, and coverage limits can be very different from the protection originally included with a new car.
The important point is to know who is actually responsible for paying your claim. Do not assume that a plan sold at a dealership is automatically managed by the vehicle manufacturer. Ask who provides the coverage, who approves repairs, and where the vehicle can be serviced. You should also understand when the extra protection begins. Paying for coverage that largely overlaps with a factory warranty can reduce its value because you may be paying for protection during a period when your vehicle is already covered.
What Does an Extended Warranty Usually Cover?
Most extended warranties are designed to protect against unexpected mechanical or electrical failures rather than normal ownership expenses. Basic plans commonly focus on the engine, transmission, and other drivetrain components. More complete plans may also include steering components, suspension parts, fuel system components, cooling systems, air conditioning, and important electrical equipment. Modern vehicles contain many costly electronic parts, so electrical coverage can be especially important when comparing different plans.
However, a part should never be considered covered until you confirm it in the contract. Some plans use a named component approach, which means only the parts specifically listed are protected. Other plans offer broader coverage and instead provide a list of exclusions. Broader plans can be easier to understand because most vehicle systems are included unless the contract specifically removes them. Even then, drivers should read the exclusions carefully because a single condition can sometimes decide whether a large repair bill is approved or rejected.
Major Repairs That Can Make Coverage Valuable
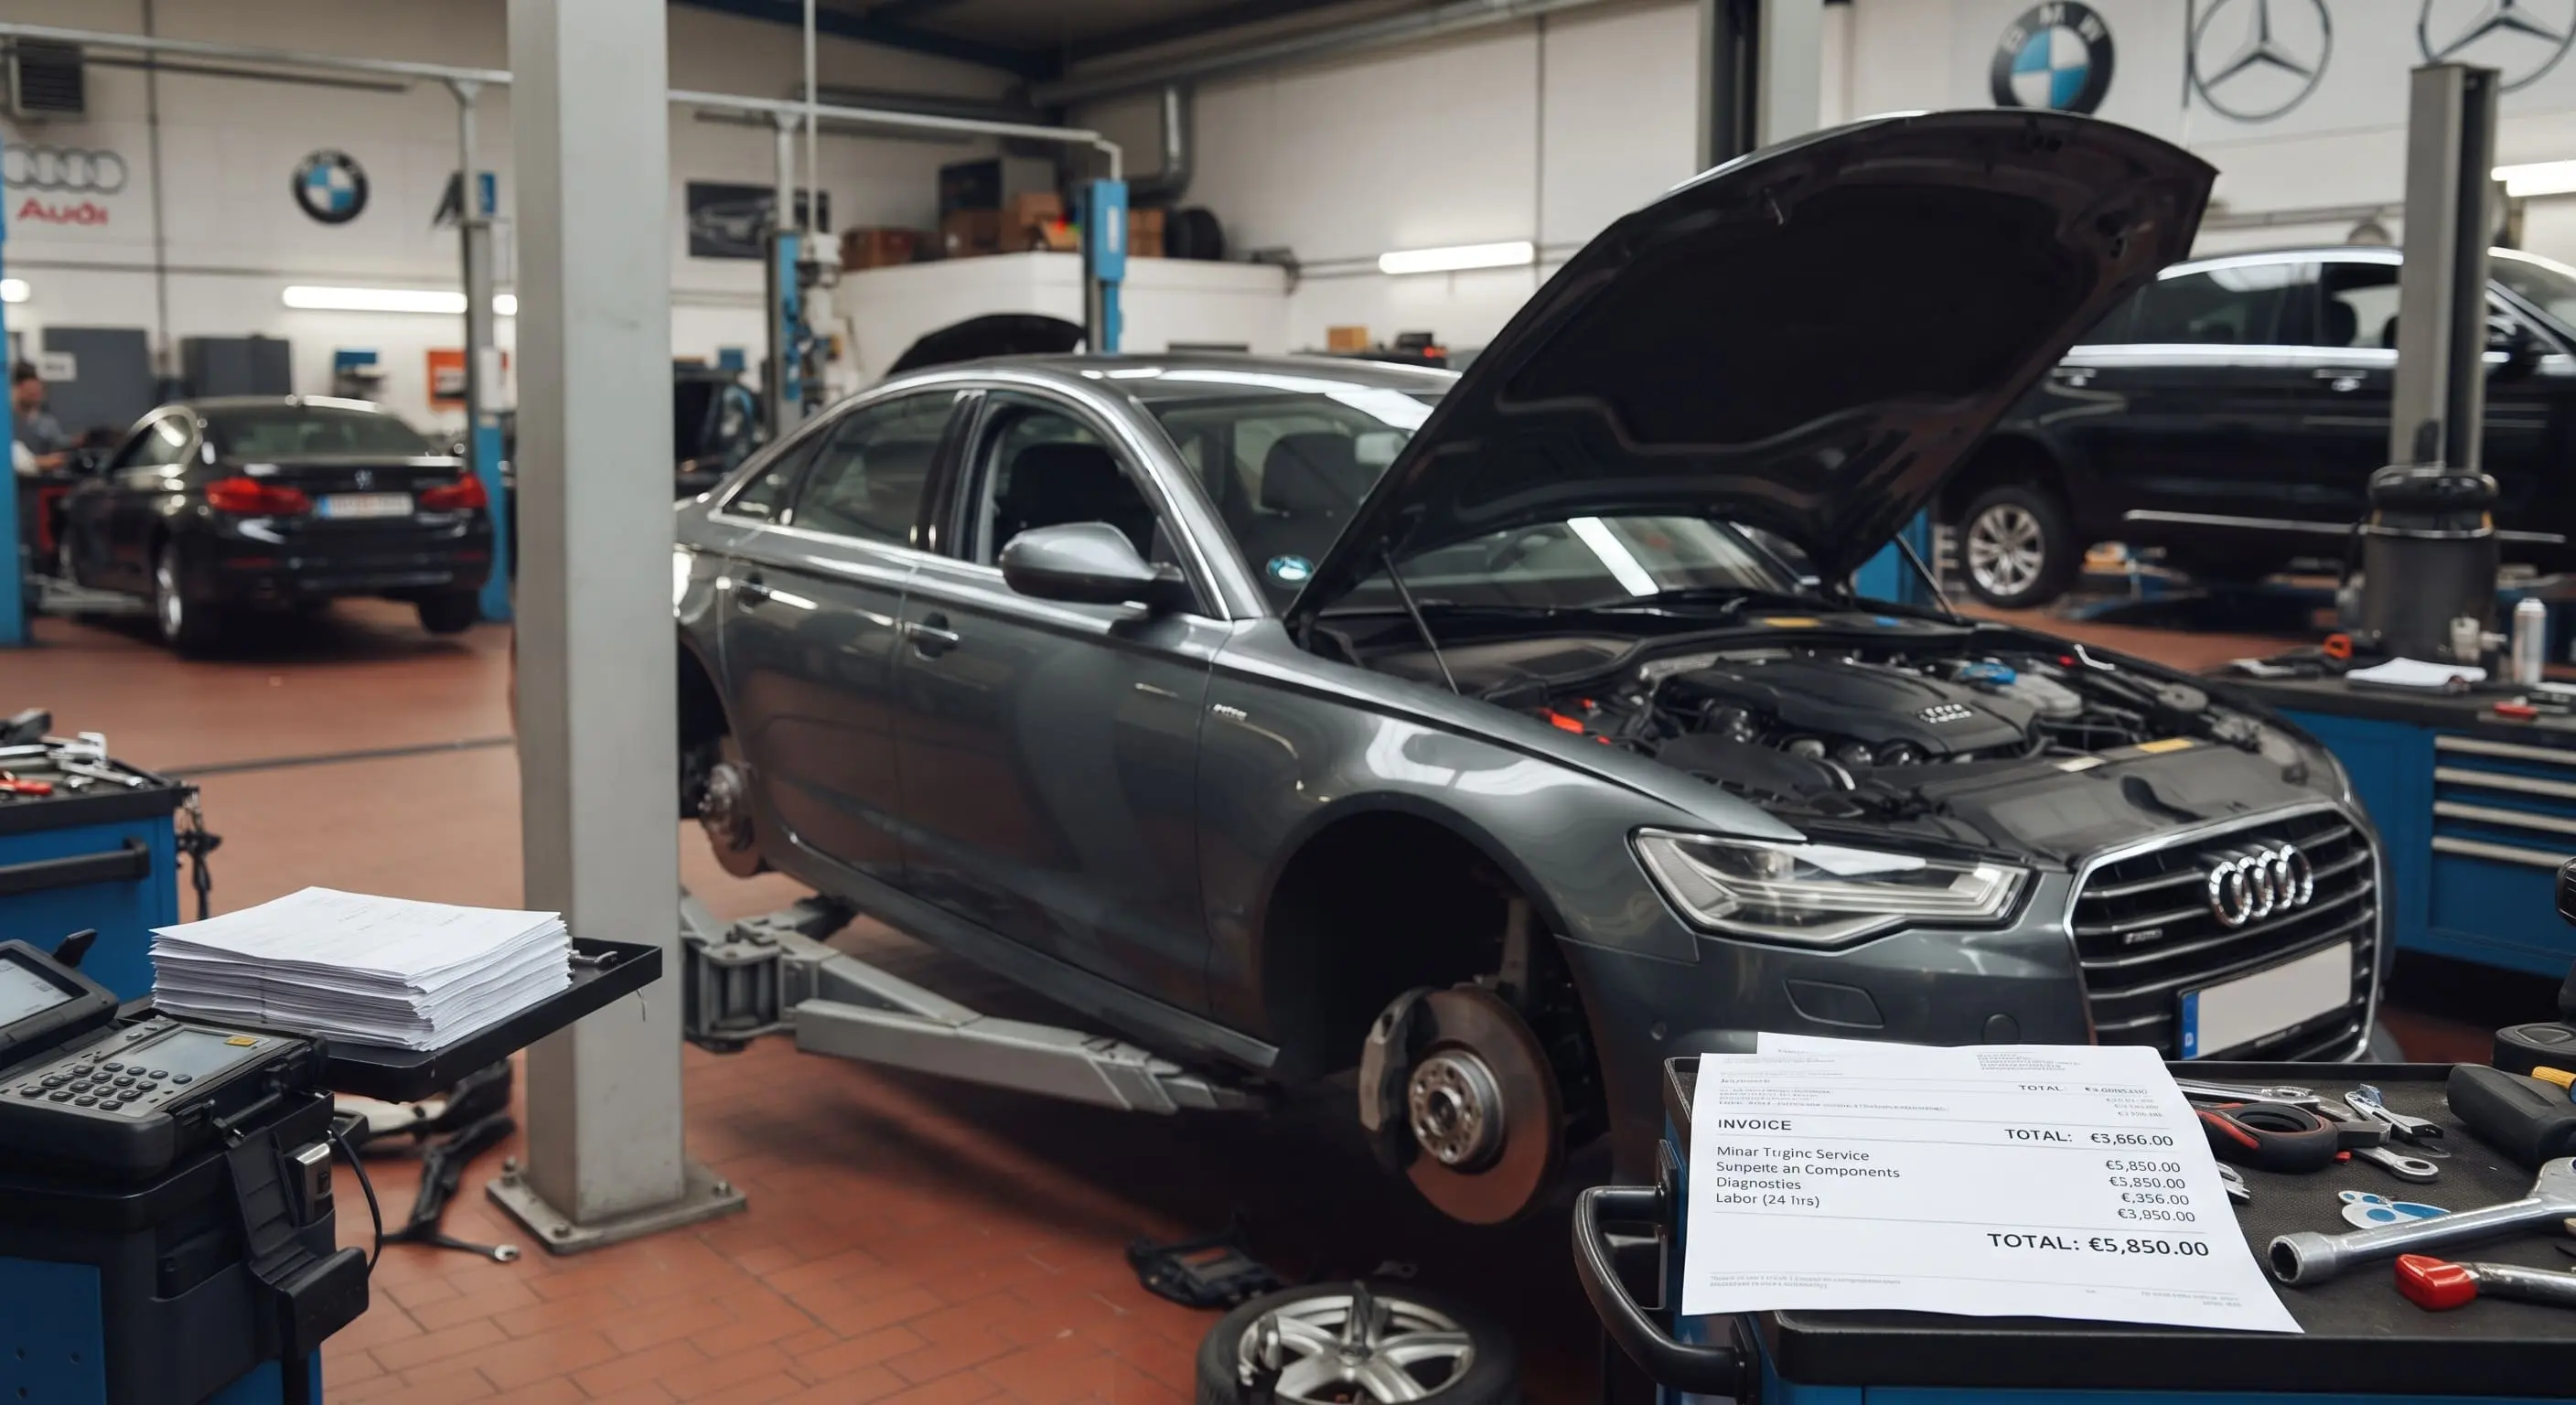
The strongest reason to buy an extended car warranty is protection against a repair that would seriously affect your budget. An engine, transmission, air conditioning system, steering system, or major electrical component can be expensive to repair. Modern cars also contain cameras, sensors, control modules, digital displays, powered seats, and other electronic equipment. When a plan covers these systems properly, it can reduce the financial shock caused by a sudden mechanical failure.
This does not mean every covered repair makes the warranty a good deal. You must compare the total price of the plan with the protection it provides. A contract that costs a large amount but has a high deductible and limited coverage may still leave you paying much of the repair bill yourself. A stronger plan should protect the parts that are expensive to repair and should have clear rules about labor, replacement parts, diagnosis costs, claim approval, and where repairs can be completed.
What Is Usually Not Covered?
Routine maintenance is one of the biggest areas of confusion. Most extended warranty plans are not designed to pay for normal services such as oil changes, tire replacement, filters, fluid changes, or regular inspections. Many also exclude parts that naturally wear out through normal driving. Brake pads, tires, wiper blades, bulbs, and similar items are usually considered normal ownership expenses. Some contracts may offer separate maintenance benefits, but drivers should never assume these services are automatically included.
Damage caused by accidents is also normally handled through car insurance rather than an extended warranty. Cosmetic problems such as scratches, dents, damaged upholstery, and faded paint are generally outside normal mechanical coverage. Problems that existed before the contract began may also be excluded. Poor maintenance can create another problem. If a covered component fails because the owner ignored required maintenance, the warranty company may challenge the claim. Keeping maintenance records and service receipts can therefore be very important.
When an Extended Warranty Becomes Wasteful
An extended warranty can become wasteful when you pay for protection that you are unlikely to use. One common example is duplicate coverage. If your vehicle still has several years of strong factory protection, an additional plan that begins immediately may provide little extra value during that period. The same problem can happen when a plan covers only a limited number of components that are unlikely to fail while excluding the expensive systems you actually want protected.
Extra benefits can also look attractive while adding little real value. Roadside assistance, towing support, rental car benefits, and trip assistance may sound impressive, but you may already have some of these services through your insurance, vehicle manufacturer, credit card, roadside membership, or another service. Paying twice for similar benefits does not improve your protection. Before buying a warranty package, check what services you already receive and focus on the repair coverage that would actually protect your budget.
How to Decide Whether an Extended Warranty Is Worth It
The right decision depends heavily on your vehicle and your finances. Start by considering how long you plan to own the car. If you normally replace your vehicle before the factory warranty expires, additional protection may have limited value. If you plan to keep the car for many years and drive it well beyond its original warranty period, extra coverage may become more useful. Reliability also matters. A vehicle with a strong history of dependable ownership may create a different risk than a model known for expensive repairs as it ages.
Your ability to handle an unexpected repair bill is another important factor. Some drivers prefer paying for coverage because a predictable warranty cost feels easier to manage than a sudden large repair. Other drivers would rather put the same money into a repair savings fund and use it only when needed. Neither approach works for everyone. The useful comparison is the total warranty cost, including any deductible and fees, against your vehicle's likely repair needs and your ability to pay for those repairs yourself.
Questions to Ask Before You Buy
Before buying any extended car warranty, ask exactly what components are covered and what is excluded. Find out when coverage begins, when it ends, and whether both time and mileage limits apply. Ask how much the deductible is and whether you pay it once per repair visit or for every separate problem. You should also know whether diagnosis charges are covered. A repair can become expensive even before work begins if you must pay for testing or disassembly yourself.
You should also ask where the vehicle can be repaired and whether approval is required before the mechanic starts working. Find out whether the provider pays the repair shop directly or expects you to pay first and request reimbursement. Ask what happens if you sell the vehicle, whether the coverage can be transferred, and whether transfer fees apply. Finally, research the company responsible for the contract. Good coverage has little value if the claims process is extremely difficult or the provider has a poor record of handling customer repairs.
Conclusion
Extended warranties can provide useful protection, but they should not be treated as automatic purchases. The best plans protect expensive mechanical and electrical components, have clear contract terms, reasonable deductibles, and a simple claims process. They can be especially useful for drivers who plan to keep their vehicles after the factory warranty ends and who want protection from a large unexpected repair bill. The value comes from covering real financial risk, not simply from having another warranty document in the glove box.
Wasteful coverage usually appears when the plan duplicates protection you already have, excludes too many important parts, charges high fees, or includes benefits you do not need. Before signing anything, compare the price of the contract with the repairs it actually covers. Read the exclusions, understand the claim rules, and consider your vehicle's reliability and ownership plans. An extended car warranty should solve a financial problem for you. If the numbers and coverage do not make sense, keeping that money available for future repairs may be the smarter choice.
Written by Maarukh Shahbaz
Published Sep 30, 2026 in Buying Guides.