Navigating the automotive financing landscape in 2026 has become increasingly complex as buyers weigh shifting federal benchmark interest rates against their monthly household budgets. When you are ready to drive a new or certified pre-owned vehicle off the lot, the method you choose to fund the purchase dictates your total financial obligation far beyond the initial down payment. Two primary contenders dominate the borrowing space: traditional dealership financing and credit union car loans.
For decades, car buyers faced a simple binary choice between a local bank and the dealership's finance office. Today, however, the financial stakes are higher. Macroeconomic fluctuations have pushed interest rates into a territory where every decimal point translates to hundreds, if not thousands, of dollars in cumulative interest charges over a standard 60- or 72-month loan term. The central dilemma facing modern consumers is balancing the convenience of showroom-floor financing against the consistently lower baseline borrowing costs offered by member-owned cooperative financial institutions.
While major automotive manufacturers frequently roll out promotional zero-percent APR incentives to move inventory on specific models, these deals are strictly reserved for buyers with pristine, top-tier credit scores. For the average consumer, credit unions consistently deliver lower baseline interest rates, highly transparent lending terms, and zero hidden markup fees compared to standard commercial automotive lending networks. Understanding how these two financial avenues operate, where their hidden costs lie, and how to leverage one against the other is the single most effective strategy for minimizing your total borrowing expenses and securing the lowest possible annual percentage rate.
Understanding Dealership Financing (Captive Lenders & Dealer Markup)
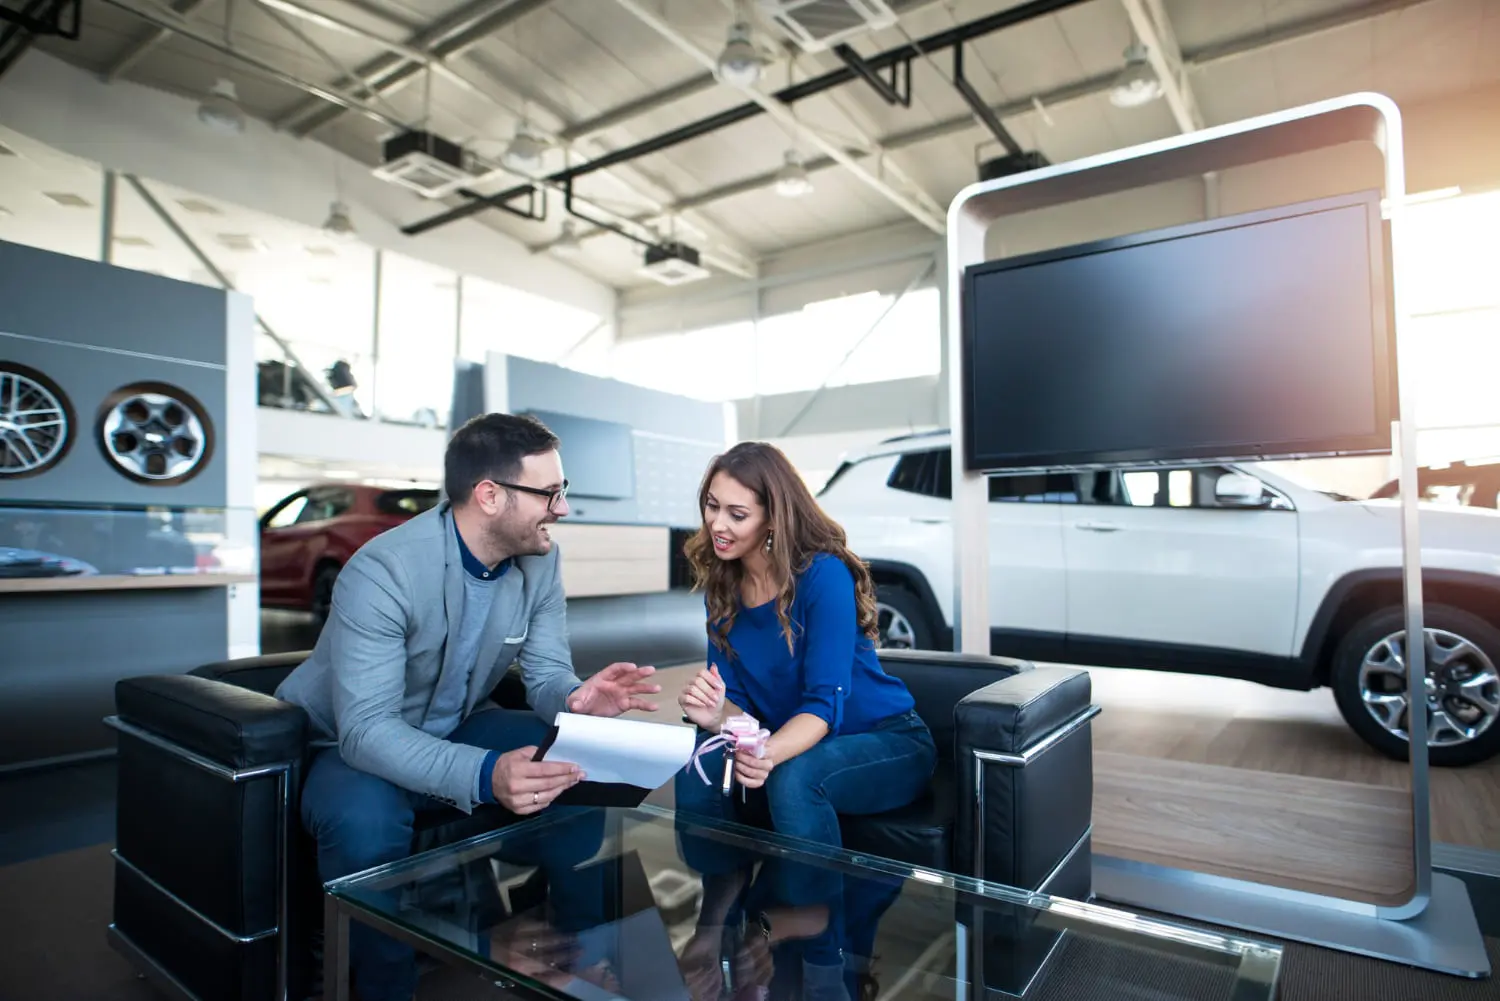
When you walk into a modern car dealership, the showroom floor is designed to keep your focus entirely on the vehicle's aesthetic appeal, features, and monthly payment rather than the actual structure of the loan. Behind the scenes, however, dealership financing operates through a complex network of financial partners known as captive lenders such as Ford Credit, Toyota Financial Services, or GM Financial alongside an array of third-party regional and national banks. Captive lenders are manufacturer-affiliated financial institutions specifically created to help dealerships move inventory off the lot by offering specialized incentives, promotional rates, and localized leasing programs.
However, standard dealership financing often introduces a hidden cost mechanism known as the dealer markup. When an F&I (Finance and Insurance) manager submits your credit application to multiple lenders, they may receive back a "buy rate," the lowest interest rate the lender is willing to offer based on your credit profile. The dealer is then legally permitted to mark up that interest rate by a certain margin (typically between one and two percentage points) and present it to you as your approved rate. This markup goes straight into the dealership's profit margins, turning what seems like an official bank rate into an inflated loan product.
Evaluating the true pros and cons of dealership financing reveals a stark contrast between short-term convenience and long-term costs. On the positive side, captive lenders frequently run aggressive promotional zero-percent APR or low-interest incentives to clear out aging model-year inventory. Furthermore, dealership financing offers unmatched, one-stop-shop convenience; you can test drive a vehicle, negotiate the purchase price, and finalize the paperwork all under one roof within a single afternoon, often bundling manufacturer rebates directly into your financing package.
Conversely, the downsides can be substantial. Dealership baseline interest rates for buyers who do not qualify for promotional tiers are significantly higher than credit union averages. Additionally, the high-pressure environment of the F&I office frequently leads to aggressive upselling of ancillary products such as heavily marked-up GAP insurance, tire protection packages, and extended warranties, which are often rolled into the principal loan balance, compounding interest charges over the entire loan term.
The Power of Credit Union Car Loans
While commercial dealership networks lean heavily on flashy promotional banners and showroom convenience, credit unions operate on an entirely different economic model that fundamentally benefits the consumer. As non-profit, member-owned cooperative financial institutions, credit unions do not answer to external corporate shareholders seeking to maximize returns. Instead, any financial surplus generated by a credit union is funneled directly back to its members in the form of higher savings yields, fewer account fees, and, most importantly, significantly lower baseline auto loan interest rates. Because they operate locally or within digital-first regional networks, credit unions carry substantially lower structural overhead than massive national commercial banks or captive dealer lenders, passing those savings directly onto car buyers.
Qualifying for a credit union car loan is often far more personalized and forgiving than dealing with automated commercial banking algorithms. If your credit score sits in the fair-to-good range rather than the elite top tier, a credit union loan officer is far more likely to look at your overall financial picture, stable employment history, and member loyalty rather than automatically kicking back a high-risk rejection or inflating your rate. This human-centric underwriting process makes credit unions an exceptional resource for everyday buyers who might otherwise get penalized by rigid commercial lending criteria.
Analyzing the distinct advantages and potential limitations of credit union financing highlights why they remain a favorite among savvy financial planners. On the positive side, baseline auto loan interest rates at credit unions routinely trend one to three percentage points lower than standard commercial bank or dealership baseline rates. Furthermore, credit union loans are entirely free of hidden dealer markups, origination surprises, and predatory backend product upselling. You receive a clean, transparent loan structure with predictable monthly payments and clear amortization schedules.
On the downside, credit unions do come with a couple of logistical hurdles. Membership is traditionally required to secure a loan, meaning you must meet specific criteria such as living in a certain geographic region, working in a specific industry, or joining a local nonprofit affiliate. However, many modern credit unions have drastically relaxed these rules, offering easy digital membership loopholes that anyone can clear within minutes. Additionally, securing a credit union loan requires separate legwork: you must apply for pre-approval independently before you shop, rather than letting the dealership handle everything on the spot.
Head-to-Head Comparison: APRs, Fees, and Flexibility
When choosing between a dealership finance office and a credit union, the decision ultimately boils down to hard numbers, credit tier eligibility, and hidden fee structures. In the current automotive market, interest rates fluctuate based on federal benchmark policies, but the structural spread between these two borrowing sources remains remarkably consistent. Understanding how your specific financial profile maps to these differences is critical to avoiding hundreds of dollars in unnecessary interest charges over the life of your loan.
To evaluate where you are most likely to secure the lowest APR, it helps to break down the primary variables across distinct borrower categories:
-
Top-Tier Credit Borrowers (Credit Score 740+): If your credit history is pristine, dealerships often hold a major competitive edge through manufacturer-backed promotional programs. Captive lenders frequently subsidize loans down to 0% or low single-digit APRs to push specific inventory. If you qualify for these factory incentives, a credit union will struggle to beat a true 0% promotional rate. However, if no promotional rate is available on the vehicle you want, credit union baseline rates for top-tier borrowers still frequently undercut standard commercial lender tiers.
-
Good-to-Fair Credit Borrowers (Credit Score 580–739): For the vast majority of car buyers who fall outside the elite promotional tier, credit unions pull far ahead. Dealership baseline rates for non-promotional financing often feature built-in dealer markups that add 1 to 2 percentage points onto the wholesale "buy rate" provided by the bank. Credit unions eliminate this middleman markup entirely, offering flat, non-profit baseline rates that can save mid-tier borrowers thousands of dollars in total interest.
-
Fee Structures and Ancillary Costs: Dealership loans frequently carry electronic registration fees, documentation charges, and administrative processing fees packaged into the financing. Furthermore, the F&I closing room is notoriously high-pressure when it comes to selling backend add-ons like GAP insurance, tire protection plans, and extended service contracts. Credit unions offer transparent loan agreements with zero hidden administrative markups, and while they may offer optional GAP protection, it is typically priced at a fraction of the cost charged by commercial dealerships.
Ultimately, evaluating your credit standing before shopping allows you to pinpoint whether a manufacturer's promotional zero-percent offer is genuinely within reach or if a credit union pre-approval will serve as your most cost-effective baseline option.
How to Leverage a Credit Union Pre-Approval at the Dealership
Walking into a dealership armed with a pre-approval letter from your credit union transforms your position from a passive consumer into an empowered negotiator. Too many car buyers make the mistake of letting the finance and insurance office handle everything from scratch, inadvertently walking into inflated interest rates and hidden dealer markups. By securing a fixed-rate pre-approval letter ahead of time, you establish a concrete financial baseline that the dealership must actively work to beat if they want to secure your financing business.
The execution strategy begins before you ever set foot on a physical showroom lot. You submit a loan application directly to your local or digital-first credit union, locking in a specific competitive APR and a maximum borrowing cap. Once approved, the credit union provides you with a draft or formal pre-approval certificate. When you negotiate your vehicle purchase, keep your financing separate from the vehicle price negotiation. Settle on the absolute lowest "out-the-door" price for the car first, and only when the purchase price is finalized should you introduce your financing option.
Once you enter the F&I office, present your credit union pre-approval draft as your primary financing choice, but give the dealer one clean opportunity to compete. State clearly: "I am pre-approved through my credit union at X percent APR. If your captive lender or partner banks can beat this rate, I am happy to finance through you right now." Because finance managers make commission on the interest rate markup, they will often check with secondary or tertiary lenders to see if they can drop the rate by a quarter or half a percentage point to win your business.
Timing your application correctly is also essential for protecting your credit profile. Multiple hard inquiries from different car dealerships over several weeks can ding your credit score. Fortunately, credit scoring models like FICO treat multiple auto loan inquiries made within a targeted window (typically 14 to 45 days) as a single inquiry. However, applying for your credit union pre-approval shortly before you shop ensures your credit report reflects a clean, single pull, giving you maximum leverage without unnecessary score volatility. If the dealer cannot beat your credit union's terms or attempts to sneak administrative fees into the contract, simply smile, decline their financing offer, and complete the transaction using your credit union check.
Conclusion
When you weigh the financial implications of modern automotive financing, the path to securing the lowest annual percentage rate ultimately hinges on your credit profile and strategic timing. Dealership financing through captive lenders remains a powerful vehicle for scoring promotional zero-percent APRs or low-rate incentives, provided your credit score rests comfortably in the top tier. For these elite buyers, commercial manufacturer programs can eliminate interest costs entirely on specific model-year inventory. However, for the vast majority of consumers navigating average credit tiers, commercial dealership networks introduce hidden costs, baseline inflation, and dealer markups that quietly drain thousands of dollars from your household budget over a standard 60- or 72-month loan term.
Credit unions offer a consistently reliable alternative by championing member-owned transparency, lower baseline rates, and zero hidden markup fees. By functioning as non-profit cooperatives, they pass operational savings directly to buyers, making them an indispensable financing ally for anyone seeking predictable monthly payments and long-term borrowing economy. More importantly, you do not have to choose blindly between the two options. Securing a credit union pre-approval before you shop gives you absolute leverage inside the dealership finance office, forcing dealers to aggressively compete for your business or step aside entirely.
By separating your vehicle purchase negotiation from your financing structure, timing your credit inquiries correctly, and leveraging non-profit rates against commercial captive lenders, you retain total control over your financial transaction. Whether you ultimately drive off the lot with a manufacturer-subsidized promotional rate or a clean, low-cost credit union loan, approaching the F&I office prepared ensures you secure the lowest possible APR and protect your hard-earned money at every turn.
Written by Maarukh Shahbaz
Published Sep 1, 2026 in Comparisons.